Market Overview of the Virtual Tourism Market
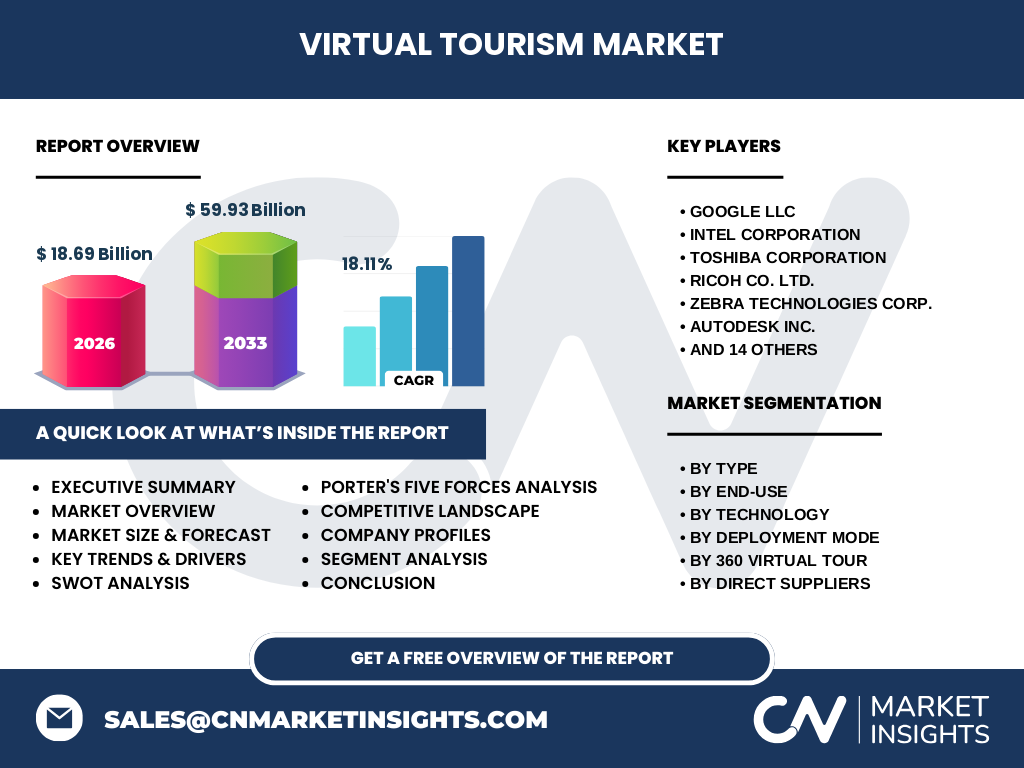
The Virtual Tourism Market is valued at 18.69 Billion in 2026, representing a paradigm shift in how global consumers interact with cultural heritage sites, hospitality properties, and entertainment destinations. Our analysis indicates that this ecosystem transcends traditional leisure by integrating advanced spatial computing to replicate physical site visits. The industry relies heavily on cloud infrastructure, specialized imaging hardware, and robust connectivity standards to deliver seamless digital explorations.
Structural Growth Drivers and Market Restraints
Growth is propelled by rapid consumer adoption of spatial audio and photogrammetry, countered by high bandwidth costs and regulatory hurdles regarding data privacy under GDPR. Infrastructure bottlenecks in developing regions restrict deployment, yet enterprise demand for remote site inspection creates resilient revenue streams for specialized technology providers.
Emerging Trends in the Virtual Tourism Market Industry Trends
The integration of real-time 3D scanning and photogrammetry is transforming the Virtual Tourism Market industry trends landscape. Industry players increasingly combine haptic feedback hardware with cloud-based distribution models to elevate user immersion. This technical evolution shifts consumer expectations from static visual galleries toward interactive, physics-enabled digital twins of physical destinations.
COVID-19 Impact Analysis and Recovery Trajectory
The pandemic served as an unprecedented catalyst, forcing travel operators and cultural institutions to accelerate digital transformation initiatives. Although physical restrictions have lifted, the resulting recovery trajectory morphed into permanent hybrid engagement strategies. Destinations that initially adopted cloud-based 360 virtual tours retained higher international visibility during the subsequent reopening phases.
Competitive Benchmarking and Market Concentration
Market concentration remains moderately fragmented, featuring major technology conglomerates alongside agile specialized software vendors. Leaders like Google LLC and Intel Corporation provide foundational hardware and mapping APIs, while niche innovators focus on bespoke photogrammetry. Strategic differentiation relies heavily on proprietary rendering engines and scalable cloud deployment capabilities.
Executive Summary of the Virtual Tourism Market Analysis
Our comprehensive Virtual Tourism Market analysis reveals a projected expansion reaching 59.93 Billion by 2033, expanding at a robust CAGR of 18.11%. This stellar growth trajectory is underpinned by surging demand across educational institutions, hospitality operators, and cultural preservation bodies seeking alternative monetization channels beyond physical capacity limits.
Virtual Tourism Market Size and Growth Forecast
Scaling from 18.69 Billion in 2026 to 59.93 Billion by 2033, the market demonstrates sustained compounding momentum at an 18.11% CAGR. This acceleration highlights capital migration toward immersive digital infrastructure, driven by falling hardware costs and rising consumer appetite for remote experiential content.
Segmentation Analysis of the Virtual Tourism Market
The market breaks down across several distinct pillars. By Type: 360 Virtual Tour, Three-Dimensional (3D) Virtual Tour, and Virtual Reality Tour. By End-Use: Travelers And Tourists, Hospitality And Accommodation, Cultural And Historical Sites, Entertainment And Recreation, Education And Training, and Other End-Uses. By Technology: Three-Dimensional (3D) Scanning And Imaging, Photogrammetry, Computer Vision, Haptic Feedback, Spatial Audio, and Other Technologies. By Deployment Mode: Cloud-Based and Web-Based. Sub-segments include Single and Multiple Location 360 Tours, Hotel Campaigns, Tour Operators, Government Bodies, Immersive and Non-immersive VR, plus 3D Static and Interactive Tours.
Geographic Distribution and Regional Market Performance
Regional performance is heavily skewed toward digitally mature economies with robust 5G infrastructure and widespread VR headset penetration. North America and Europe dominate consumption due to high concentrations of cultural heritage sites and advanced hospitality marketing budgets, while Asia-Pacific exhibits the fastest adoption velocity driven by government-backed smart tourism initiatives.
In-Depth Regional Review
North America leads in revenue generation, bolstered by enterprise adoption from key players like Zillow Group and Autodesk Inc. Meanwhile, European markets prioritize regulatory-compliant cultural archiving, leveraging technologies from Leica Geosystems AG to digitize historical monuments under strict regional data protection frameworks.
Strategic Positioning of Leading Companies
Industry leaders maintain distinct strategic positioning. Trimble Inc. and Zebra Technologies Corp. focus on industrial-grade 3D scanning and spatial data capture, whereas consumer-facing platforms like Kuula Inc. and Vieweet optimize web-based tour publishing for hospitality campaigns and independent tour operators.
Porter's Five Forces Analysis
Competitive rivalry is intense, driven by rapid technological commoditization. Threat of substitution remains moderate as physical travel returns, though enhanced sensory immersion via haptic feedback mitigates this risk. Supplier power is low regarding basic software tools, but high for specialized LiDAR hardware manufacturers.
SWOT Analysis of the Virtual Tourism Ecosystem
Strengths include scalable cloud deployment and rich spatial audio capabilities. Weaknesses stem from high initial content creation costs. Opportunities lie in educational metaverse integrations, while threats involve cybersecurity vulnerabilities and potential user fatigue regarding unoptimized virtual environments.
Value Chain Analysis from Raw Materials to End-Users
The value chain originates with raw sensor manufacturers and semiconductor fabricators, flows through software developers utilizing computer vision algorithms, and terminates via cloud-based distribution channels managed by hotel campaigns and government tourism bodies reaching end-use travelers.
Investment Insights and High-Potential Areas
High-potential capital allocation targets include photogrammetry software startups and haptic feedback R&D. Investors should prioritize firms offering interoperable web-based deployment modes that bypass burdensome hardware requirements for end-users.
Conclusion and Strategic Takeaways
The Virtual Tourism Market offers compelling growth avenues through 2033. Stakeholders must embrace cloud-native deployment and advanced 3D scanning to capture shifting consumer preferences across educational and hospitality verticals.
Research Methodology and Baseline Triangulation
Our baseline estimates are rigorously triangulated by cross-referencing trade registry databases, conducting primary stakeholder interviews with executives from firms like Ricoh Co. Ltd. and Magic Leap Inc., and synthesizing secondary macroeconomic indicators regarding global IT spending.
Scope of the Report and Coverage Parameters
This report covers global revenue streams from 2026 to 2033, analyzing technological deployment modes, end-use verticals, and regional performance. Exclusions apply to offline hardware manufacturing components not directly integrated into virtual tourism applications.
Recent Developments and Industry Announcements
Recent market dynamism includes strategic partnerships between enterprise software providers like Cupix Inc. and hospitality chains, alongside product launches by Vuzix and Blippar Group Limited aimed at enhancing augmented spatial navigation for remote tourists.